Healthcare Pharma & Life Sciences Other Industries
All Services Performance Marketing ChatGPT Ads India · NEW Social Media Marketing SEO & AEO / LLM YouTube Marketing LLM Optimization Brand & Growth Consulting AI Solutions Industries We Serve
Enterprise Hub · All Solutions + Services Growth Transformation AI Transformation Revenue Operations Fractional CGO Growth Operating System Executive Growth Advisory
Clinic Launch Programme (Hub) NABH Consulting India Healthcare Brand Launch Clinic SOP Creation Logo Design (Healthcare) Brand Book Creation Clinic Launch Marketing D2C Brand Launch Clinic Interior Design
Workforce Hub For Employers — post a requirement For Professionals — register Public Openings Training Academy AI Training Flagship
Hawk · CRM Intelligence (NEW) YODA · YouTube Intelligence Angryturtle · GBP Intelligence (NEW) Prism Pulse · Instagram Analytics (NEW) Beacon · Attribution Agency OS · Dashboards Phoenix · Clinic Revenue HealthPro 360 · PMS/HMS AI Patient Lifecycle Bots AI Lead Management System Smart Appointment System Healthcare CRM Patient Feedback System AI, Analytics & Automation Digital Transformation Calculators Free Digital Health Audit →
All 13 calculators → 🎯 Business Exploration Matrix (New) Dental Clinic Setup IVF Clinic + Lab Setup Multi-Specialty Hospital Setup Aesthetic / Cosmetology Clinic Dermatology Clinic Setup Generic Clinic Setup Physiotherapy Clinic Setup Diagnostic Centre Setup CAC Calculator CPQL Calculator Franchise ROI Calculator Revenue Leakage Calculator CRM ROI Calculator
All Events Workshop 1 · Jun 13 · AI in Clinical Practice Workshop 2 · Jun 27–28 · AI in Growth & Governance Hospital Ops Workshop · Jul 12 Pre-Summit Seminar · Aug 16 Grand Summit 2.0 · Oct 10–11 Bihar AI Summit · Recap AI Innovation Awards · Aug 22 Grand Summit 2.0 · Oct 2026 Aarambh 2026 Recap
Case Studies Insights & Blog Research Reports Calculators AI in Healthcare Digest
Our Story Leaders @ Ichelon · IN · US · AU Ichelon India · Gurgaon Ichelon Consulting US · Dallas, TX Ichelon Australia · Sydney Speakers & Panelists Client Elevation Programme 🤝 Partner Connect 🇦🇪 ICG UAE Careers
Book a Growth Diagnostic →
We Do It Right. The right diagnosis. The right strategy. The right systems. Giving healthcare leaders the confidence to make better decisions, build stronger operations, and achieve sustainable growth. — Team Ichelon
US compliance pillar · TILA · Financing · 2026

Aesthetic financing TILA compliance — APR display, promotional financing, CFPB enforcement and CareCredit, Alphaeon, PatientFi and Cherry disclosure templates

A working reference for medspa owners, aesthetic practice CFOs and marketing leads who advertise patient financing through CareCredit, Alphaeon Credit, PatientFi, Cherry, Sunbit or any other third-party lender. Written against the Truth in Lending Act, Regulation Z advertising rules at 12 CFR 1026.24, the FTC Advertising Endorsement and Substantiation standard, the CFPB's UDAAP authority under the Dodd-Frank Act, and the state usury and consumer-credit statutes that create additional overlays.

Direct answer
  • The Truth in Lending Act at 15 USC 1601 and Regulation Z at 12 CFR 1026 apply to any advertisement or offer of consumer credit for personal purposes. A medspa advertisement of financing terms is subject to Regulation Z's advertising rules — irrespective of whether the medspa itself is the lender.
  • Under 12 CFR 1026.24(d), "triggering terms" — a specific down payment, a specific number of payments, a specific payment amount, or a specific finance charge — require disclosure of all applicable additional terms with equal prominence: down payment, repayment terms, and the APR.
  • Deferred-interest promotions (widely used with CareCredit and some Alphaeon Credit programmes) require additional care. Clear disclosure of the promotional period, the consequences of partial payment (all deferred interest becomes payable), and the ordinary APR is mandatory. CFPB enforcement patterns in healthcare financing have concentrated here.
  • Third-party financing partners — CareCredit (Synchrony), Alphaeon Credit (Comenity), PatientFi, Cherry, Sunbit — each publish practice-facing marketing kits with pre-approved copy. The kits are a floor, not a ceiling. Where practice advertising deviates from the pre-approved copy, the practice takes on the compliance burden itself.
  • State usury laws, consumer-credit statutes and credit-services organisation acts create additional overlays. Practices operating in multiple states should confirm whether any state-specific registration or licensing applies to the financing referral pattern.
The ICG engagement model
Every practice welcome — retainers starting from $499/mo.
Goals-Driven engagements · Performance-Linked Payout Models available. Read the full engagement model →
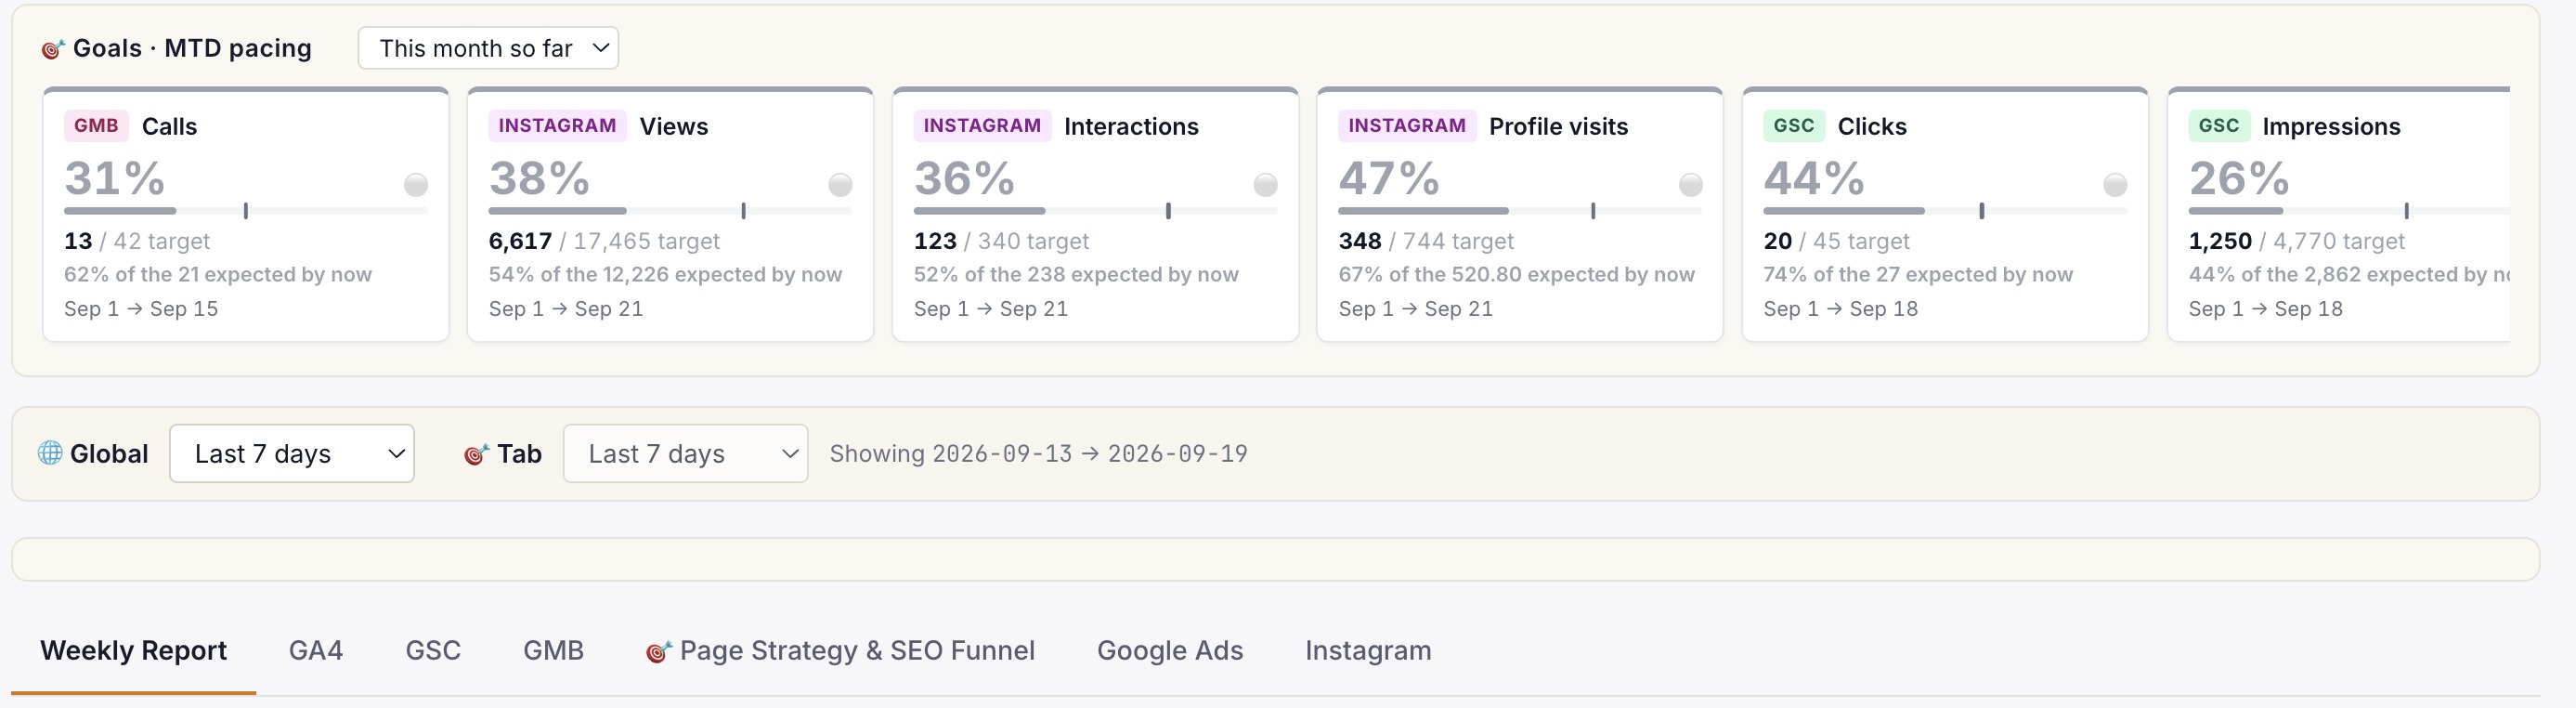
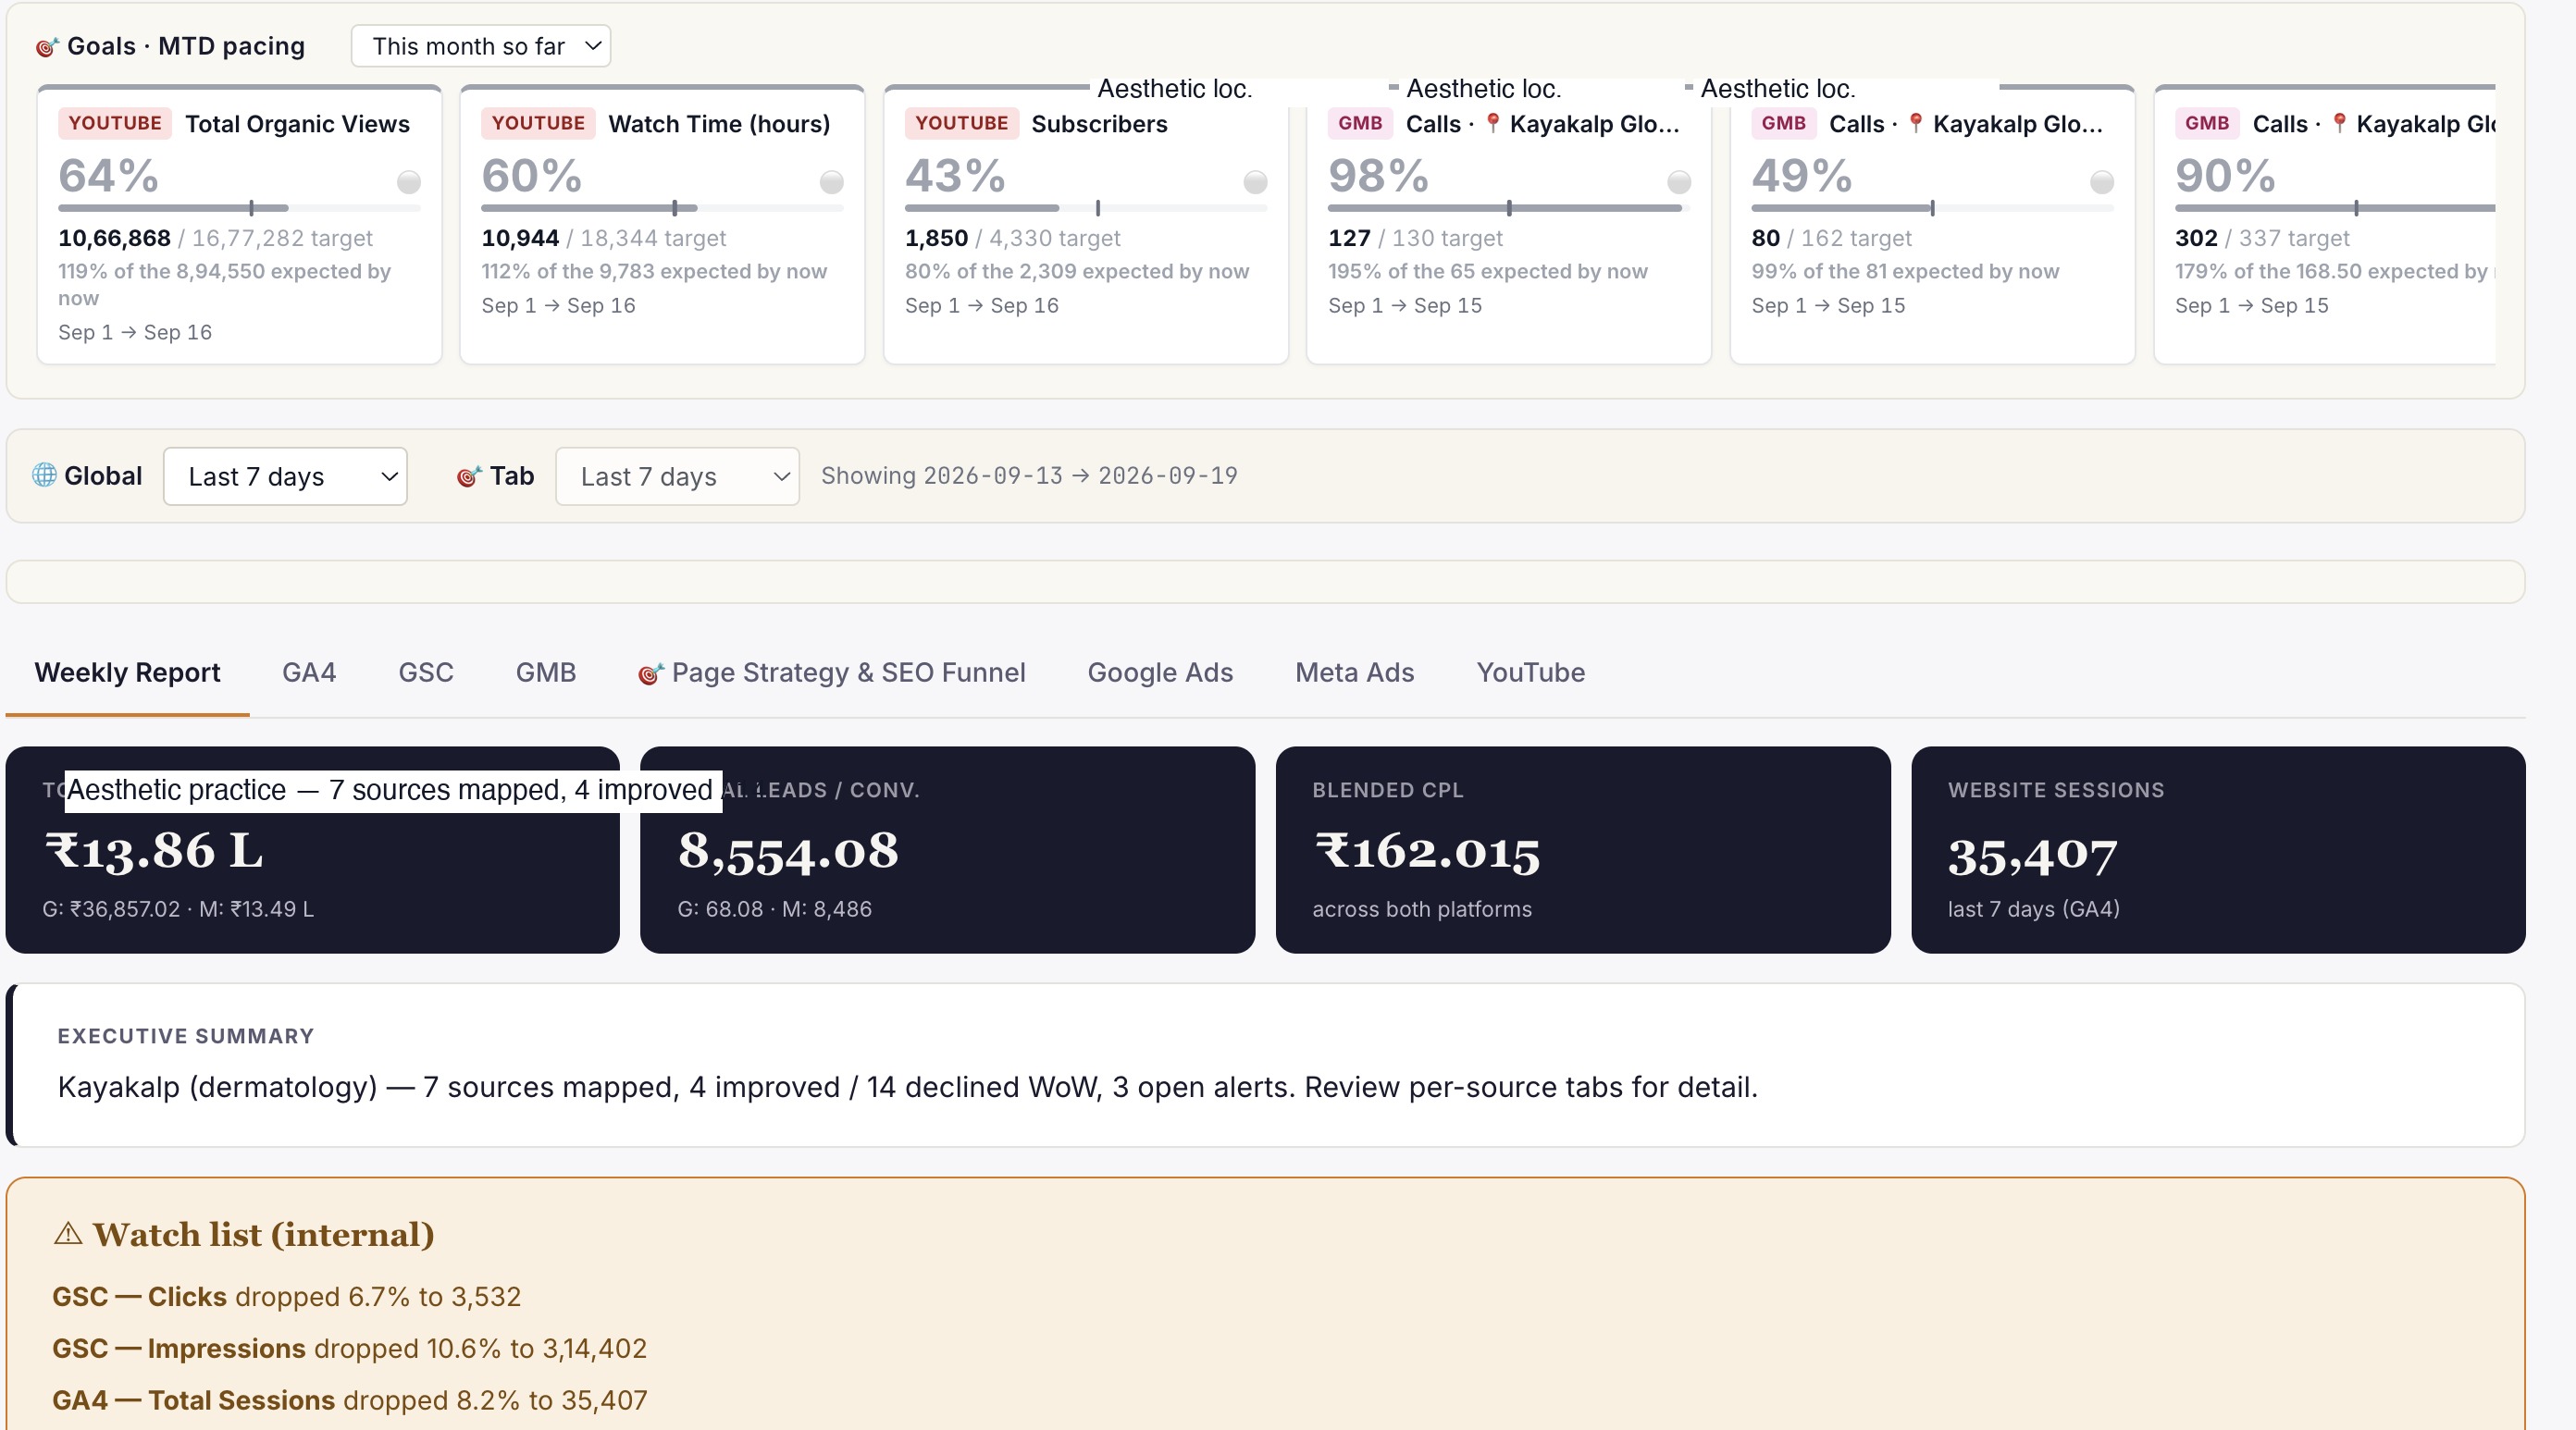
🎯 Ichelon Agency OS See your goals live · client-facing dashboard, updated in real time. Click any screenshot to zoom. Open the full engagement model →
Trusted by US practices · case studies → 8 live practices · TX · CA · VA · nationwide telehealth
Dr. Rajan Kohli
Owner, Lakewood Primary Care & Wellness · North Dallas, TX
Client video · Practice website build
“They were able to get all my ideas and work with me over a period of three to four months and create this amazing website. It's super customized, very modern, and it incorporates all the elements that I had wanted — the patient portal, nice pictures, a very interactive website, patient reviews. I would highly recommend their company to anyone who wants to make an excellent website.”
Dr. Rajan Kohli Owner, Lakewood Primary Care & Wellness · North Dallas, TX
Foundation

Why aesthetic practice financing advertising is TILA-scoped

The Truth in Lending Act was enacted in 1968 as the consumer-protection anchor for the modern credit industry. Its purpose, at 15 USC 1601, is to ensure the meaningful disclosure of credit terms so consumers can compare offers and avoid uninformed use of credit. Regulation Z at 12 CFR 1026, promulgated by the Federal Reserve and now administered by the CFPB, provides the operational rules — including the advertising rules at 12 CFR 1026.16 for open-end credit and 12 CFR 1026.24 for closed-end credit.

Regulation Z applies to advertisements about consumer credit even when the party making the advertisement is not itself the creditor. A medspa that runs a Google ad or a Facebook ad, or that publishes a landing page or a brochure, advertising a specific promotional financing offer is publishing an advertisement of consumer credit. The rules attach.

Who is a creditor

A person becomes a creditor under Regulation Z at 12 CFR 1026.2(a)(17) generally when they extend consumer credit that is subject to a finance charge or that is payable by written agreement in more than four instalments, and they are the person to whom the debt is initially payable. Most medspas route financing through third-party lenders precisely to avoid becoming creditors themselves — the compliance and licensing overhead of being a creditor is substantially higher than the compliance overhead of being an advertiser of another party's credit product.

Citation: 15 USC 1601 et seq.; 12 CFR 1026 (Regulation Z); 12 CFR 1026.24 (closed-end credit advertising); 12 CFR 1026.16 (open-end credit advertising); Dodd-Frank Act UDAAP authority at 12 USC 5531; CFPB Circular 2022-01 on deceptive representations.
Triggering terms

The four triggering terms that force additional TILA disclosures

Regulation Z at 12 CFR 1026.24(d)(1) lists four specific "triggering terms." If an advertisement of closed-end credit states any of them, the advertisement must also disclose the additional terms in 12 CFR 1026.24(d)(2) with equal prominence.

The triggering terms

  • The amount or percentage of any down payment.
  • The number of payments or period of repayment.
  • The amount of any payment.
  • The amount of any finance charge.

The required additional disclosures

  • The amount or percentage of the down payment.
  • The terms of repayment, which reflect the repayment obligations over the full term of the loan, including any balloon payment.
  • The annual percentage rate, using that term or the abbreviation "APR." If the APR may be increased after consummation, the ad must state that fact.

The equal-prominence requirement is not casual. A Google ad headline reading "Botox from $99/month" — even without additional financing details — is stating a specific payment amount, which is a triggering term. The APR must appear in the same asset with equal prominence. A footnote in a smaller font is not equal prominence. An asterisk pointing to a link that discloses the APR on a subsequent page is not equal prominence.

Common failure pattern. A medspa runs a paid social campaign with the creative "$149 per month for Botox — 0% APR for 12 months." The 0% APR statement is itself a triggering term (specific finance charge). The ad must also disclose the down payment (or state there is none), the terms of repayment including what happens after the 12-month promotional period, and — for a deferred-interest structure — the ordinary APR that applies. Missing any of these is a Regulation Z advertising violation.
Deferred interest

Deferred-interest promotions — the CFPB’s central healthcare-financing concern

Deferred-interest financing is the aesthetic-vertical bread and butter. CareCredit's classic promotion is "no interest if paid in full within 6, 12, 18 or 24 months on purchases of $200 or more." Alphaeon Credit and several other healthcare-adjacent lenders offer similar structures. Deferred interest is not the same as 0% interest. In a 0% interest promotion, no interest ever accrues on the promotional balance. In a deferred-interest promotion, interest accrues from the transaction date at a stated APR but is waived if the balance is paid in full by the promotional deadline. If the balance is not paid in full, all deferred interest becomes payable.

The CFPB has taken the position, most notably in a series of consent orders in the mid-2010s and again in enforcement priorities restated more recently, that deferred-interest advertising must clearly disclose the deferred-interest consequences. Advertising that promotes "0% interest" language on a deferred-interest product without clearly explaining what happens if the balance is not paid off has been treated as deceptive under both TILA and the UDAAP prong of Dodd-Frank.

What a compliant deferred-interest disclosure looks like

  • Clear labelling as "deferred interest" rather than "0% interest" or "no interest."
  • Statement of the promotional period.
  • Clear statement of what happens if the balance is not paid in full: "If the full amount is not paid by the end of the promotional period, interest will be charged from the transaction date."
  • Disclosure of the ordinary APR that applies to the account.
  • Disclosure of the minimum monthly payment and a statement that minimum payments alone will not pay off the promotional balance in time.
  • Applicant-approval qualifier — "subject to credit approval" — placed with equal prominence.
Lender-specific templates

Working templates for CareCredit, Alphaeon, PatientFi and Cherry

CareCredit (Synchrony)

CareCredit is the largest healthcare-financing brand in the aesthetic vertical. Synchrony publishes an approved-marketing library that gives providers pre-approved copy, badges and creative. Practice-facing compliance responsibility is highest when the practice deviates from the approved kit. The workable template for a practice landing page is:

  • Headline states the option — "CareCredit financing available."
  • Body states the promotional structure — "6, 12, 18 and 24-month deferred-interest financing on purchases of $200 or more, subject to credit approval."
  • Body states the ordinary APR — the exact figure supplied by Synchrony in current marketing materials.
  • Body states the deferred-interest consequence — "If the promotional balance is not paid in full by the end of the promotional period, interest will be charged from the transaction date at the standard APR."
  • Applicant-approval qualifier — "Subject to credit approval. Minimum monthly payments required."
  • Lender identification — "CareCredit is a healthcare credit card issued by Synchrony Bank."

Alphaeon Credit (Comenity)

Alphaeon Credit is Comenity's aesthetic-focused product line. Its promotional structure mirrors CareCredit in the deferred-interest and standard-APR posture. Practice landing pages should identify Alphaeon and Comenity as the issuer, disclose the promotional-period range offered, the ordinary APR, the deferred-interest structure and the credit-approval qualifier.

PatientFi

PatientFi generally offers instalment loans with fixed monthly payments and a stated APR rather than deferred-interest revolving credit. The disclosure architecture is different — a fixed APR range disclosed with equal prominence, term length, and total cost of credit. Because the product is a closed-end instalment loan, the 12 CFR 1026.24 triggering-term analysis applies directly.

Cherry

Cherry offers instalment plans across a range of merchants including aesthetic practices. Landing pages should state the APR range (Cherry publishes tiered APR bands based on credit tier), the term options, whether any promotional 0% APR is available and its qualifying conditions, and the credit-approval qualifier. Cherry's practice-facing marketing kit provides pre-approved language; deviation shifts compliance responsibility to the practice.

CFPB enforcement

The CFPB layer — UDAAP, examinations and typical enforcement patterns

The Consumer Financial Protection Bureau administers TILA on the enforcement side, and separately has authority under the Dodd-Frank Act to bring unfair, deceptive or abusive acts or practices (UDAAP) actions against covered persons and service providers. Healthcare financing has been a recurring enforcement priority since the mid-2010s and remains so.

Typical enforcement patterns have included:

  • Consent orders against issuers for inadequate deferred-interest disclosures.
  • Consent orders against merchants for advertising promotional terms in a way that misled consumers about the true APR or the deferred-interest consequences.
  • Restitution orders returning charges to affected consumers, often in the tens of millions of dollars in aggregate.
  • Civil money penalties and injunctive relief covering merchant advertising practices.

For an aesthetic practice, the exposure surface is at the intersection of Regulation Z advertising (fixed rules that produce specific per-violation exposure) and UDAAP (a broader deception-and-unfairness standard that reaches practices Regulation Z does not enumerate). Programme design should satisfy both.

Safe pattern. Use the lender's approved-marketing kit as the base. Where the practice's brand voice requires deviations, run every deviation through the lender's provider-support desk for approval before publish. Retain the approved copy in the marketing library with a version stamp. Audit annually against current lender kits — lenders update their kits when regulators press them on disclosure.
Fix these first

Five decisions every aesthetic practice’s financing programme must make

1. Which lender partners

Two or three, not seven. Every added lender adds a distinct compliance surface. CareCredit (deferred interest revolving), Alphaeon Credit (deferred interest revolving), PatientFi (fixed-term instalment), Cherry (fixed-term instalment with tiered APR) cover most aesthetic use-cases.

2. Use of pre-approved kits

Base copy from each lender's kit is safest. Any deviation goes through the lender's provider-support desk for approval. No practice-invented copy on APR, deferred-interest or promotional terms.

3. Triggering-term audit

Every ad, landing page, brochure and social post that names a monthly payment, a term length, a down payment or a finance charge triggers the four Regulation Z additional disclosures. Audit for these before publish, not after.

4. Deferred-interest disclosure standard

Every deferred-interest asset labels the product as deferred interest, states the promotional period, the consequences of partial payment, the ordinary APR, and the credit-approval qualifier. Never "0% interest" for a deferred-interest product.

5. Annual kit refresh

Lenders update their approved-marketing kits when regulators press them. The practice audit checks every financing asset against the current kit annually and retires outdated versions.

State overlays

State usury, consumer credit and credit-services overlays

The federal TILA/Regulation Z envelope is a floor, not a ceiling. State-level layers include:

  • State usury caps. Some states impose maximum APRs on consumer loans; interstate lenders often rely on federal preemption or specific state exemptions. The relevance to a medspa is limited because the lender bears the usury exposure, not the advertiser.
  • State consumer-credit statutes. Some states have their own analogues to TILA that apply additional disclosure or licensing requirements.
  • Credit-services organisation statutes. A handful of states regulate businesses that arrange credit for consumers. Whether these statutes reach a merchant that simply presents third-party financing to a customer varies state by state.
  • State attorney general UDAP. Every state has an unfair and deceptive acts and practices statute that can be brought by the state attorney general. Aesthetic-financing advertising that misleads consumers is a live target under these statutes.

A practice operating in a single state can generally focus on federal Regulation Z plus that state's attorney general UDAP posture. A practice operating in multiple states should audit each state's specific overlay before scaling a national campaign.

Federal envelope

Where TILA sits in the medspa marketing stack

TILA Regulation Z CFPB UDAAP State UDAP FTC HIPAA TCPA (SMS follow-up) CAN-SPAM (email drip) ADA
Our research · State of Med Spa Google Presence 2026

What we found when we studied 555 US med spas on Google

Patients praise the care almost without exception. The one area where complaints outnumber praise is booking and communication, and that is where most med spas can win.

4.87★
average Google rating. Near-perfect ratings are table stakes.
5.83
median new reviews per month. Most profiles grow slowly.
~54%
of booking and communication reviews are negative, the one weak theme.

Full study · 555 US med spas across 20 metros · roughly ±4% nationally · review velocity and themes from a 115-spa subsample · verified against raw data.

Leadership

Backed by Ichelon Consulting US leadership

Every aesthetic financing programme review is conducted alongside the Leadership Team's senior US practice reviewer, with visibility into CareCredit, Alphaeon Credit, PatientFi and Cherry provider-support workflows and CFPB enforcement pattern history.

The ICG technology stack

Nine tools. One compounding system. HealthApex OS
Built in-house. Deployed in every engagement.

ICG's results are reproducible because they are built on proprietary infrastructure — not agency intuition or generic tools. These nine HealthApex OS platforms are what power every ICG engagement.

WhatsApp AI

LynxFlow

WhatsApp AI Lead Qualifier

An AI assistant that holds a short WhatsApp conversation with every enquiry, decides whether it fits your criteria, and posts qualified leads to your CRM labelled Qualified. Team inbox, campaigns and consent handling included. $40/mo for US practices.

Explore LynxFlow →
Business Layer

Hawk

CRM Intelligence & Lead-Ops MIS

Sits as the business intelligence layer above your CRM — AtomCRM or any other CRM you run, including custom builds. Shows where leads are leaking, which effort is wasted, and which good leads were quietly downgraded by automation — not by a human decision.

  • Sits above your existing LMS — no replacement
  • 83% of effort goes to dead leads — surfaced Day 1
  • ~75% qualified-lead downgrades by automation
  • Free Lead-Leak Audit in 48 hours
Explore Hawk + free audit →
Attribution Core

Beacon

Attribution Engine & CAPI Middleware

Sits at the centre of every ICG attribution architecture. CAPI middleware connecting Meta Ads, Google Ads, WhatsApp and IVR to your CRM. Lifts Event Match Quality from 2.5 to 6+, reducing CPM 30–40% from the same budget.

  • Server-side CAPI — bypasses iOS privacy changes
  • EMQ 2.5 → 6+ across portfolio
  • 30–40% CPM reduction from EMQ lift alone
  • Multi-touch: ad → consultation → revenue
Explore Beacon →
Practice Management

HealthPro 360

PMS with built-in revenue intelligence layer

A PMS built to track cross-sell and up-sell opportunities within your existing patient base. 12 modules covering OPD, IPD, Pharmacy, Labs, Billing, Inventory, Patient Portal, Smart Scheduling, RBAC, AES-256 encrypted storage.

  • Only PMS with built-in Revenue Intelligence
  • Cross-sell signal tracking within existing patients
  • 12 modules: OPD, IPD, Pharmacy, Labs, Billing+
  • Audit trails + RBAC + AES-256 encryption
Explore HealthPro 360 →
Revenue Layer

Phoenix

Revenue intelligence built over your existing PMS

If you already have a PMS, whichever one it is, Phoenix builds the business intelligence layer on top of it without replacement. Built for single clinics and multi-centre chains alike.

  • Works over your existing PMS — no migration
  • Daily action queue: Prevent Loss / Maintain / Grow
  • Catches unbilled services, collection gaps, lapsing patients
  • CPQL variance ₹620–₹3,800 → ₹680–₹1,420
Explore Phoenix →
YouTube Intelligence

YODA

YouTube analytics that measures patients, not views

A YouTube intelligence platform built for healthcare business outcomes. Connects video performance to actual consultation bookings — not views, not subscribers. Patient testimonial videos generate 6.9× more consultations per view than condition explainers.

  • Consultation attribution per video — not views
  • Demand-gap: what patients search that your channel misses
  • 50+ doctor channels tracked across India
  • AIO readiness scoring: which videos AI tools cite
Explore YODA →
Governance & Transparency

Agency OS

Full transparency. Instant diagnosis. Zero surprises.

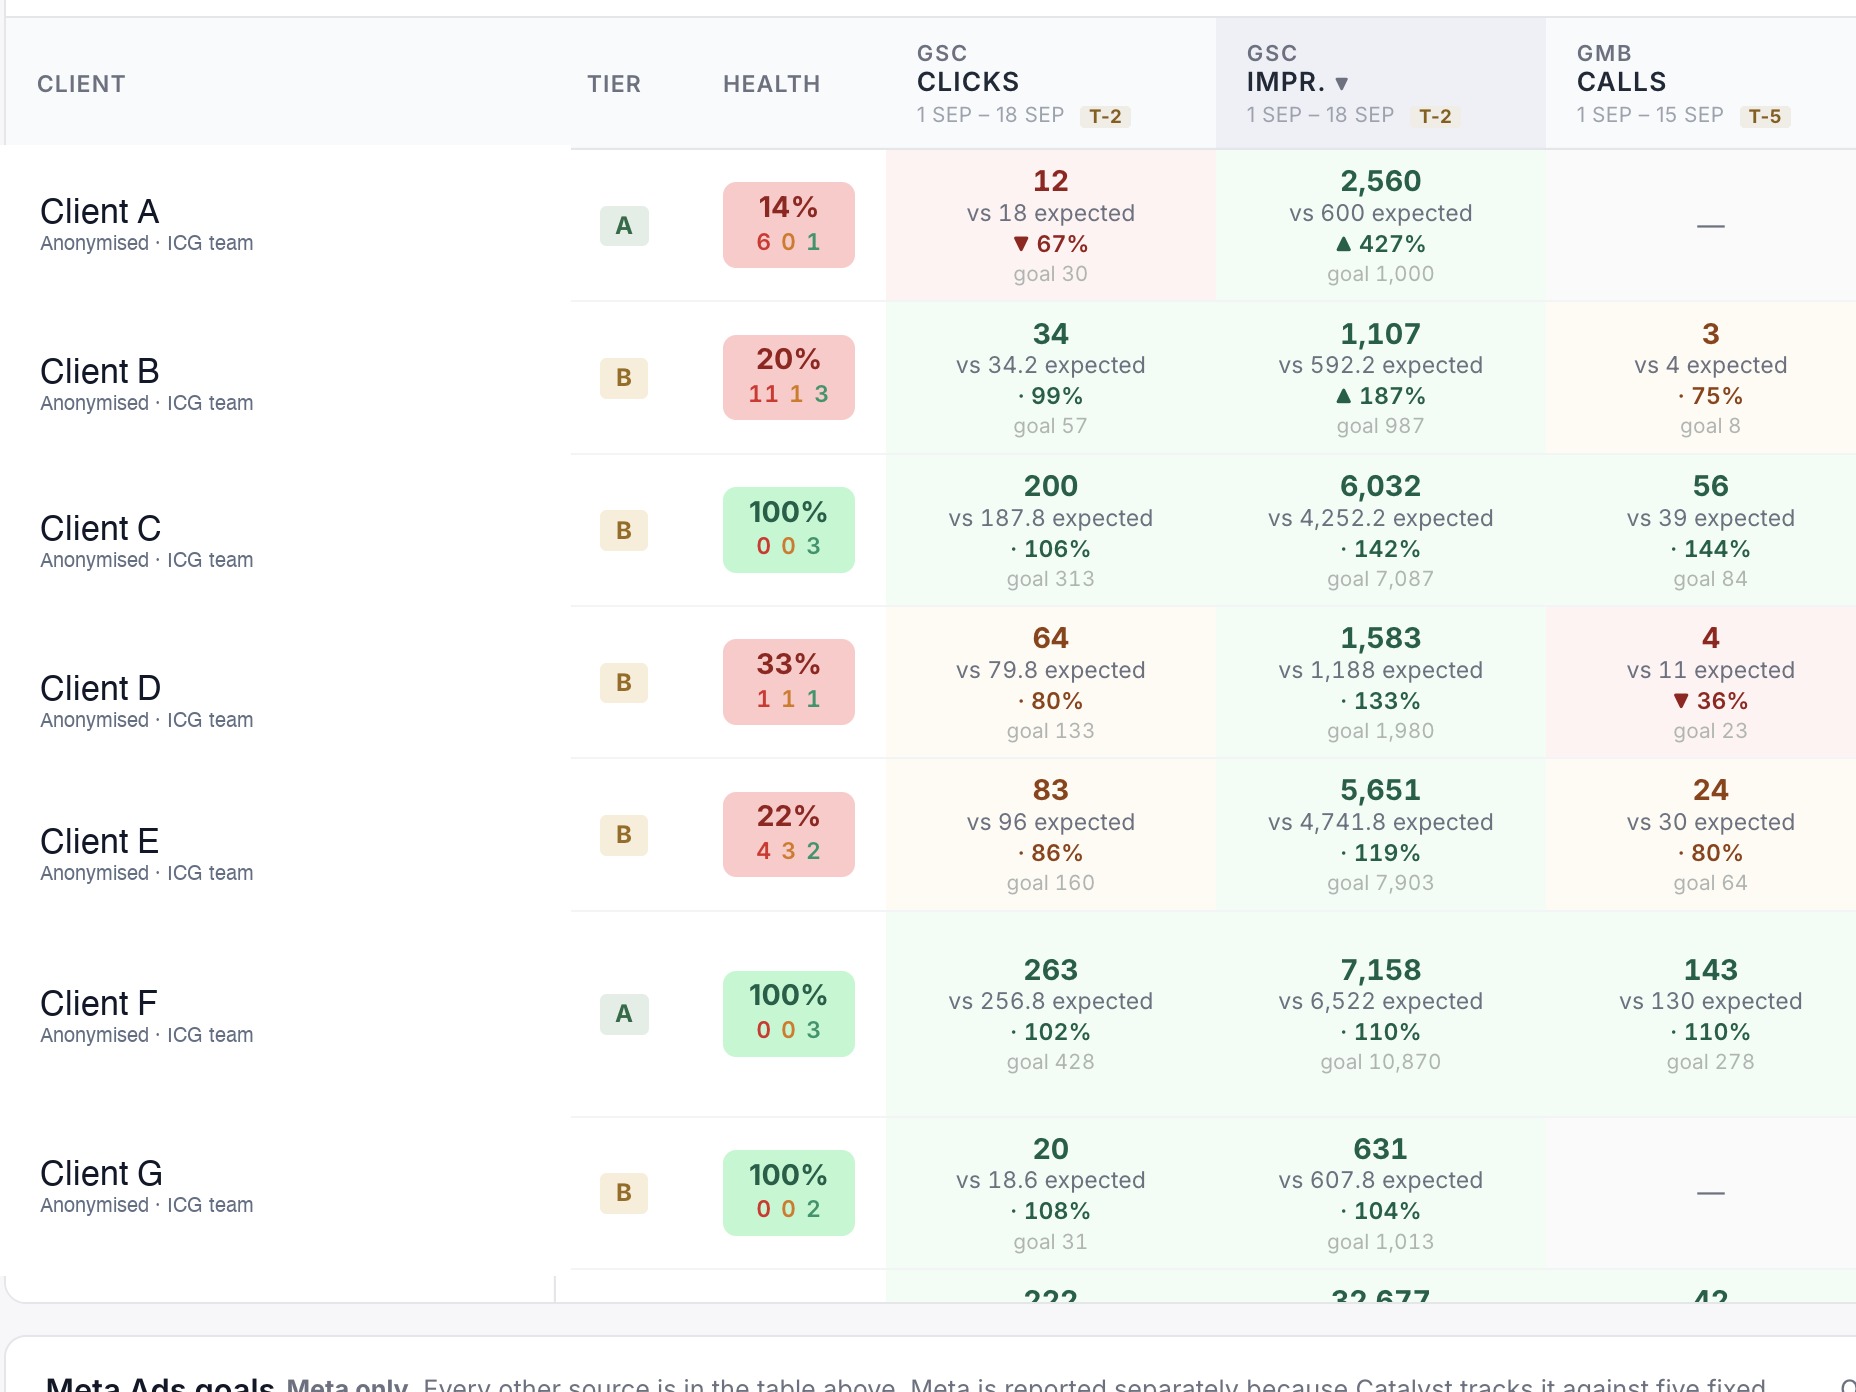
ICG's centralised governance platform — every client sees everything in real time, and ICG's team sees every problem the moment it surfaces. 30+ real-time alert systems fire the moment a metric drifts outside its performance envelope.

  • GSC, GA4, Google Ads, Meta Ads, IVR — one live view
  • 30+ real-time alert systems per account
  • CPQL drift alert at >15% week-on-week change
  • Client login: full transparency on your account
Explore Agency OS →
AEO & LLM Intelligence

AIO Intel

AI Overview + LLM citation tracking, healthcare-tuned

Knows the moment ChatGPT, Perplexity, Google AI Overviews and Gemini cite your brand in patient answers — and which content drove the citation. Bot-aware dashboard with GA4-registered custom dims (AIO source, AIO referrer) and IndexNow + GSC API integration.

  • Live tracking across ChatGPT / Perplexity / Google AIO / Gemini
  • Bot-aware: knows human vs scraper traffic
  • Custom GA4 dims register AIO source + referrer
  • IndexNow + GSC API: content surfaced to LLMs within hours
View AIO Intel dashboard →
Competitor Intelligence

Prism Spy

Every Meta + Google ad your competitors run, watched daily

Tracks 75+ Indian healthcare brands, 2,150+ active ads, ₹50Cr+ aggregate ad spend visibility per month. Surfaces what's working, what's been killed, what offers are emerging. Powers every ICG Meta Ads brief, Performance Marketing diagnostic, and IVF / derm / dental specialty campaign with real competitive intelligence.

  • 75+ brands tracked across 30+ healthcare specialties
  • 2,150+ active ads · daily refresh
  • Activity Feed: every spend / hook / pause logged
  • Offers Intelligence: 250+ offers in market tracked
Explore Prism Spy →
GBP Intelligence Platform

Angryturtle

Every Google Business Profile scored, tracked, protected, and grown from one command centre

ICG's proprietary Google Business Profile intelligence platform. Scores every listing across 7 dimensions, tracks rank on a live geo-grid across your actual service area, audits NAP + citations, monitors 531 suspension-risk factors continuously, and drafts Google Posts on cadence. Currently managing 143 healthcare listings with 0 suspensions and 4.76★ portfolio average across 28,137 reviews.

  • 143 listings under management · 0 suspensions · 4.76★
  • 7-dimension Health Score + 5-factor Rank OS per listing
  • Geo-grid rank tracking + NAP + Citation audit + Profile Shield
  • NMC + NABH + ART Act + DPDP compliance built into every content + review workflow
Explore Angryturtle →
Every ICG engagement runs on some combination of these ten HealthApex OS tools. The diagnostic determines which combination is right for your practice.

Explore HealthApex OS → See the full stack live on your account — free 30-min audit →
FAQ

Aesthetic financing TILA — common questions

Does the Truth in Lending Act apply to medspa financing?

Yes. TILA at 15 USC 1601 and Regulation Z at 12 CFR 1026 apply to any advertisement or offer of consumer credit for personal purposes, including a medspa ad for CareCredit, Alphaeon, PatientFi or Cherry financing.

What triggering terms activate additional TILA disclosures?

Down-payment amount or percentage, number of payments or repayment period, payment amount, or finance charge. Under 12 CFR 1026.24(d), each triggers the four required disclosures.

Do we need to disclose the APR alongside the monthly payment?

Yes. When the ad states a specific monthly payment, the APR must be disclosed with equal prominence in the same asset.

What is deferred interest and how does it affect disclosure?

Deferred interest is interest that accrues from the transaction date but is waived only if the balance is paid in full by the promotional deadline. Advertising must clearly state the consequence of partial payment, the promotional period and the ordinary APR.

What does the CFPB actually enforce?

TILA compliance and, separately, UDAAP under the Dodd-Frank Act. Typical enforcement patterns in healthcare financing target deferred-interest disclosure and merchant advertising overstatement.

Do medspas need to be licensed as a credit broker?

Generally no for a merchant that refers to a third-party lender, but some states have credit-services organisation statutes that reach merchants who arrange credit. Multi-state practices should confirm state by state.

Can medspas offer their own in-house financing?

A merchant that extends credit with a finance charge or more than four instalments becomes a creditor under Regulation Z. Most practices route financing through third-party lenders to avoid lender-level obligations.

What is a compliant financing landing page structure?

Product, lender, APR range, terms, deferred-interest structure and consequences if applicable, applicant-approval qualifier, effect of missed payments, and a link to the lender's full disclosure.

Do lender-provided marketing kits satisfy compliance on their own?

They are a strong floor. Deviating from the kit shifts responsibility to the practice. Run every deviation through the lender's provider-support desk for approval before publish.

How often should financing copy be audited?

Annually at minimum, and whenever the lender updates its approved-marketing kit. Retire outdated versions from the marketing library at each refresh.

Scope your TILA-compliant financing programme

Book a 30-minute call with a senior member of the Leadership Team, email the US practice lead, or call the Dallas office. Retainers are custom-scoped per engagement · from USD 250 per month equivalent, with financing copy audits priced on scope.

Selected ICG clients

Healthcare brands ICG
has worked with.

A representative slice of the 150+ healthcare brands ICG has delivered for across India. Full client list available under NDA during a Brand and Growth Diagnostic.

Read full client case studies →

Chat with Sr. Leadership
🎯 Goals-Driven engagements · Performance-Linked Payout Models
Chat with Sr. Leadership