Insurance pages that convert: a guide for primary care practices
For most people choosing a primary care doctor, insurance is the first filter. If your website can't tell them quickly whether you take their plan, many move on to the next practice without calling. A well-built insurance page is one of the highest-value pages on a primary care website, and one of the most neglected.
- Replace "we accept most major insurance" with a list of plan names, as patients see them on their cards.
- Give Medicare, Medicare Advantage, Medicaid and marketplace plans their own clear sections.
- Explain self-pay options and the patient's right to a Good Faith Estimate.
- Consider individual pages for your largest plans to match "doctor that takes [plan]" searches.
- Put a "last reviewed" date on the page and keep it in sync with your Google Business Profile and directories.
- Every practice welcome — retainers from $499/mo, Goals-Driven engagements, Performance-Linked Payout Models available.
-
 Primary Care · North Dallas, TXCase study →
-
 MedSpa · North Dallas, TX
-
 Skin Care · Beverly Hills, CA
-
 Dental · Christiansburg, VACase study →
-
 Pediatrics · Blacksburg, VACase study →
-
 Pediatric Dentistry · Blacksburg, VACase study →
-
 Dental · Roanoke, VACase study →
-
 Functional Medicine · Telehealth · USACase study →
“They were able to get all my ideas and work with me over a period of three to four months and create this amazing website. It's super customized, very modern, and it incorporates all the elements that I had wanted — the patient portal, nice pictures, a very interactive website, patient reviews. I would highly recommend their company to anyone who wants to make an excellent website.”
"We accept most major insurance" is costing you patients
Look at the insurance page on most primary care websites and you'll find a sentence like "We accept most major insurance plans. Please call our office to verify coverage." It feels safe. It isn't. It pushes the most important question a new patient has onto a phone call, during office hours, with hold time. Plenty of people won't make that call. They'll check the next practice instead.
A vague insurance page also causes problems after booking. A patient assumes "most major insurance" includes their plan, arrives for the visit and learns it doesn't, or that their carrier's marketplace plan isn't accepted even though its employer plan is. That patient doesn't come back, and they might leave a review about it.
A specific insurance page solves both problems. It is also a strong search asset, because people search for doctors by plan name.
What a converting insurance page includes
- A direct answer at the top. "We are in network with the plans listed below and are accepting new patients" (if true). Add a search box or a jump list if the list is long.
- Commercial plans, by name. The names patients see on their cards, grouped by carrier. Where a carrier has several products (HMO, PPO, EPO), list which you accept.
- Medicare section. Say whether you accept Original Medicare, and list the Medicare Advantage plans you're in network with. Many older patients search for exactly this, and Medicare Advantage networks vary widely.
- Medicaid section. If you accept Medicaid, list the managed-care plans by name. If you don't, say so kindly and, if you can, point people to the state's provider directory.
- Marketplace plans. Plans bought through HealthCare.gov or a state marketplace often have narrower networks than the same carrier's employer plans. Be explicit.
- Self-pay and Good Faith Estimates. Explain self-pay options, publish common prices if you choose to, and tell uninsured and self-pay patients they can request a Good Faith Estimate, as the No Surprises Act requires.
- How to confirm and what to bring. A short checklist: call the number on your card, bring the card and ID, know your primary care assignment if your plan requires one.
- A booking button and a "last reviewed" date. The page's job is to move people to booking. The date builds trust and reminds your team to update it.
Per-plan pages: matching how patients search
Patients type searches like "primary care doctor that takes [plan] near me", "[Medicare Advantage plan] PCP [city]" and "family doctor accepting Medicaid [city]". A single insurance list helps, but for your largest plans, a dedicated page can do far more.
A good per-plan page is not a copy of the main list with the plan name swapped in. It should include:
- Which of that carrier's products you accept, and any you don't.
- Whether the plan requires a primary care assignment or referrals, and how to name your practice as their PCP (with a pointer to the plan's own instructions).
- Which of your locations and providers are in network for that plan.
- What new patients should expect at their first visit, such as an annual wellness visit for Medicare patients.
- A booking button and the date the information was last checked.
Start with the three to five plans that cover most of your patients. Add more only when you can keep them current. Before using carrier names or logos in advertising, check your contracts, as some plans set rules on how providers may reference them.
Consistency across every source
Patients cross-check. Make sure your website, Google Business Profile description and posts, the plans' own provider directories and your front-desk scripts all say the same thing. Directory errors are common, and a patient who sees you listed in their plan's directory, calls, and hears "we don't take that" will not try again.
Open enrollment and plan changes: the moments to be ready
Many patients change plans at predictable times: during Medicare's annual enrollment in the fall, during marketplace open enrollment, and at employer benefit renewals, often in January. Each change is a moment when patients look for a new doctor who's in their network.
- Before enrollment periods: review and update the insurance page, per-plan pages and Business Profile.
- In January: post on your Business Profile about the plans you accept for the new year, and make sure the "accepting new patients" status is current.
- When a contract changes: update the website the same week, notify affected existing patients by the channels they've agreed to, and brief the front desk.
Avoid anything that looks like steering Medicare beneficiaries toward particular plans. Your job is to state accurately which plans you accept, not to recommend one.
Design, accessibility and measurement
Insurance pages are often long lists, so design matters. Group plans under clear headings, use expandable sections on mobile, and make the booking button visible at every scroll position. Meet WCAG 2.2 AA so screen-reader users can navigate the list; our accessibility guide covers the basics.
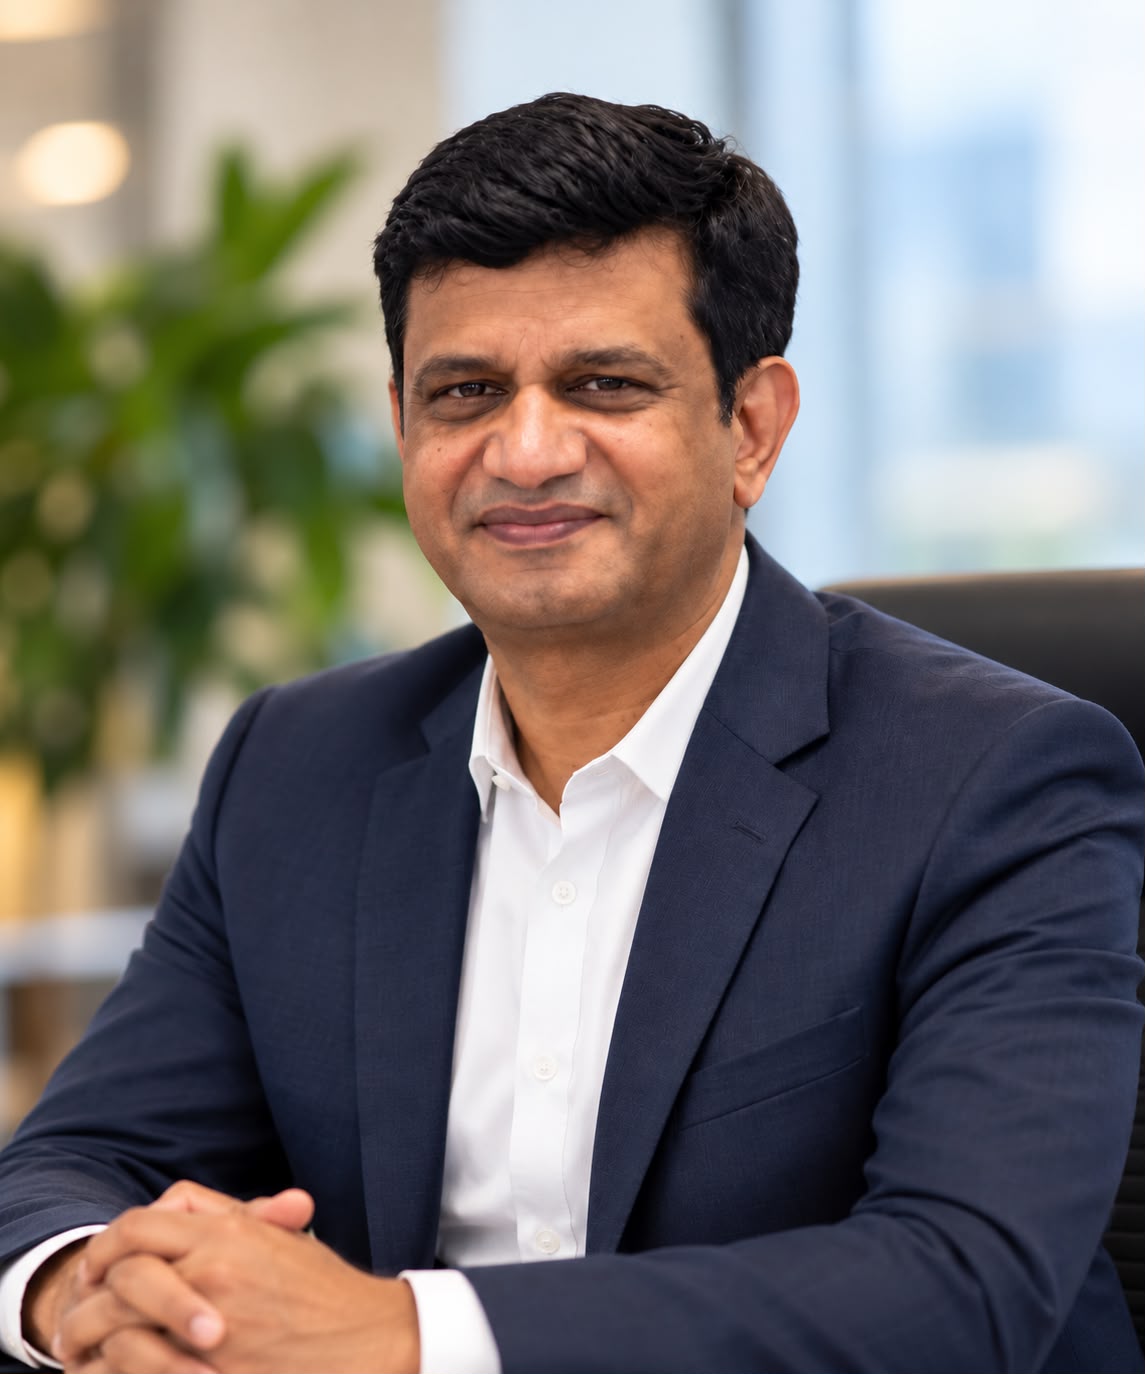
When we built the website for Lakewood Primary Care & Wellness in North Dallas with its owner, Dr. Rajan Kohli, the brief included a patient portal, patient reviews and an interactive design. Getting practical information like this into a site patients can use easily is what turns a website from a brochure into a front door.
What to measure
- Visits to the insurance page and per-plan pages, and the share that go on to book.
- Calls asking "do you take my insurance?", which should fall as the page improves.
- Check-in surprises: visits rescheduled because of insurance mismatches.
- New patients by plan, to see which per-plan pages are worth expanding.
Keep insurance details that visitors type into forms out of analytics and ad platforms. Our HIPAA-safe tracking guide explains how to measure without sharing protected health information.
Related pages from the US team
Primary care marketing USA
Our full approach for primary care practices.
Case study: Lakewood Primary Care
The website we built with Dr. Rajan Kohli for his North Dallas practice.
Healthcare marketing agency USA
How Ichelon Consulting US works with practices across the country.
Medicaid & CHIP patient acquisition
For practices that serve children with Medicaid and CHIP coverage.
Every practice welcome — Goals-Driven engagements from $499/mo
We benchmark your last 90 days, agree monthly goals with you, and track them live on Ichelon Agency OS with a report every Monday. Performance-Linked Payout Models are available. Our US leadership is based in Dallas, and strategy calls run in US business hours.
Common questions
Why does an insurance page matter so much for primary care?
Because it answers the first question most new patients have. People often begin with their plan's network and then check practice websites to confirm. If the answer is vague, they move on. A specific, current insurance page reduces calls from people you can't serve and increases bookings from people you can.
Should we list every insurance plan we accept?
List the plans patients actually recognize, using the names on their cards, grouped by type: commercial plans, Medicare Advantage, Medicaid managed care and marketplace plans. Where you accept a carrier's commercial plans but not its Medicaid or marketplace plans, say so. Precision prevents frustrating surprises at check-in.
Should we make separate pages for each insurance plan?
For your largest plans, often yes. A page for a major plan can explain which of its products you accept, how to confirm coverage and how to book, and it can match searches such as "primary care doctor that takes [plan] in [city]". Keep each page accurate and useful, not a thin copy of the others.
What do we need to tell self-pay patients?
Under the No Surprises Act, uninsured and self-pay patients have the right to a Good Faith Estimate of expected charges when they schedule or ask. Say so on your insurance page, explain how to request one and list common self-pay prices if you publish them. Check the current requirements with your billing team or counsel.
How often should the insurance page be updated?
Review it at least quarterly and whenever a contract changes, and before open-enrollment periods when many patients change plans. Put a "last reviewed" date on the page. Update your Google Business Profile, directories and front-desk scripts at the same time so every source says the same thing.
A note on this guide: it explains marketing practice, not legal advice. Rules on privacy, advertising and insurance change and vary by state, so confirm anything compliance-related with your own counsel.
Want your insurance page to bring in patients?
A 30-minute benchmarking call with the US team. We'll review your insurance and new-patient pages and tell you what we'd fix first.